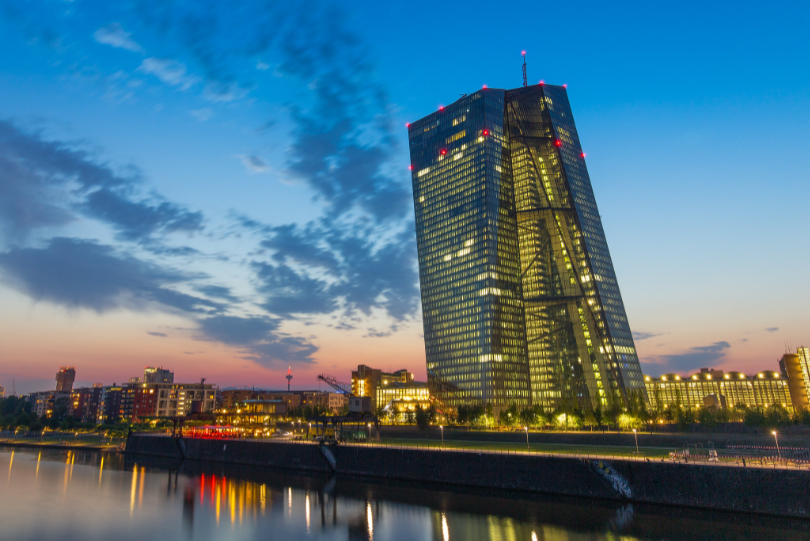
On February 22, the European Central Bank (ECB) announced it ended 2023 with a net loss of €1,266 million (U.S. $1.33 million).
It was the first loss incurred by the bank since just after the euro (€) common currency platform was announced for use in most of the European Union as of the year 2000. The ECB has always had a positive growing balance sheet for the entire period between January 1, 2022, which physical euro notes and coins were in distribution and normal use, and present day.
In the press release which accompanied the announcement, the bank acknowledged its track record of substantial profits made by the bank for most years, even while it managed its way through the economic crises of the 2008 global lending debacle which began in Europe and then spread worldwide, and even past the pandemic era of forced lock downs and resulting business closures which put major stress on other banks based in the European Union member states. What caused challenges first in a substantial way for its balance sheet in 2022 and finally pushed the bank financials into the red in 2023 were related to the challenges of excessive high inflation across the Eurozone.
The soaring inflation which affected the EU and the ECB over the last several years was different in overall causes and more severe than in any other developed economic region in the world during that period. In 2022, for example, while severe oil and gas sanctions placed on Russia did cut back on the global supply of fossil fuels, the impacts of this were felt in the EU more than anywhere else.
In the U.S., for example, where inflation spiked to 9.1% at mid-year, with gasoline, natural gas, and fuel oil costs soaring, that jump in prices was more about manipulation of prices which saw the slowing of global gas and oil supply because of Ukraine war as an opportunity to raise prices domestically and export more to countries which used to depend on Russia, rather than any real shortage. With Russia supplying only about 8% of the oil and gas the U.S. used the previous year, and with the White House incentivizing more fossil fuel production and draining the Strategic Petroleum Reserve to send cheap oil to China to benefit the Biden family, there was no economic justification for raising prices locally. All this, plus the Federal Reserve Board pushing back on forward spending by aggressively raising bank lending rates, contributed to the U.S. having an official inflation rate of 7.5% for all of 2022 (actual inflation was much higher).
While much higher than desirable, the U.S. inflation rate that year was 1.7 percentage points lower, or by ratios 18.5% less, than the EU’s 9.2% average inflation rate across the country. It also hit its high later in the year than in the U.S., so that while inflationary pressures had eased downwards from its peak of 9.1% down to 7.7% by October 2022, in Europe the opposite was happening. It had risen to 11.5% overall in the EU, rising from October’s already serious 10.9% rate.
In contrast, housing and related expenses in Europe soared by 18.0% for the year, all mostly driven by fossil fuel costs which rose almost entirely because of sanctions imposed on Russia, and therefore fully under the control of the EU to have managed differently. Higher fuel prices and some supply chain problems like ones being incurred in the United States caused transportation costs for just about everything to rise by 12.1% for the year, with ripple effects across many industries. Food and non-alcoholic beverage prices in the Eurozone were also up for the year on aggregate by 11.1%.
As with the Federal Reserve Board in the U.S., the European Central Bank’s primary reason for being is to do its best to regulate price stability and money supply throughout its jurisdiction. The ECB does this similarly to the Fed, by adjusting prime lending rates from the bank and by actively managing money supply by various means. In the case of the ECB, unlike the Fed, the bank has a central role in loaning money to major financial institution and other enterprises in the EU, while the Fed covers some of its bases by bailing out banks to protect against domino-effect like banking failures such as was thought to be about to happen in March of last year, with Silicon Valley Bank and several other major banks collapsed as a result of poor financial management practices and predatory attacks.
The European Central Bank’s practices of lending money is also accounted for differently than the way things are managed in the U.S. When for example the Trump and Biden administration issued special stimulus packages of various kinds to individuals and corporations, the monies involved were, at least with respect to the Federal Reserve Board banking system, managed to a substantial extent “off book” so they never appeared on the Fed’s balance sheet. The ECB had no such benefit and took the losses associated with keeping the continent’s economies up and running as a cost to their ongoing operations.
As a result of these three factors then – high inflation caused substantially as a result of the EU imposing harsh sanctions on a primary source of oil and gas for many member states, loans and payouts at what now appear as bargain rates to keep individual economies afloat, and that the ECB takes the hits for financial performance of all as a direct hit – the ECB was hurt bad enough to drive its long-standing track record of substantial profits to a major loss for the first time in two decades this time.
“The raising of key ECB interest rates to combat inflation in the euro area resulted in increased interest expenses on ECB liabilities that are subject to variable interest rates,” the ECB wrote in its summary describing what happened last year. “However, interest income on the ECB’s assets did not increase to the same extent or at the same pace, since those assets largely have fixed interest rates and long maturities.”
That put the bank in a difficult position, because of its charter and because of the difficult state of the economy throughout Europe.
As it noted in its detailed statements, the ECB pointed out the sharp contrast net interest results for the enterprise over the last two years. Where the net interest profit was €900 million in 2022, that had plummeted to a €7,193 million net interest loss in 2023. Those losses piled up, the bank explained further primarily because the ECB’s net target bank liability had jumped from 2022’s €2,075 million to €14,236 million in 2023, a value up by a factor of 6.9X just in a single year.
As for the future, despite that EU interest rates are now back at relatively healthy levels of 3.4% for the month of December 2023 and January 2024 cash refinance lending rates from the bank sitting at 4.5% as of January 2024, the ECB will remain affected by its challenges which began 2022 and net losses in 2023 for some time to come.
It is also possible that the European Central Bank reserves will be hit further as several countries within the EU continue to struggle with their own debt loads this year. Because the ECB is the principal “lender of last resort” to avoid further economic declines if an individual member state cannot manage issues on its own, that puts the ECB in a more tenuous position with respect to the EU’s fiscal stability than the Federal Reserve Board banking network is on behalf of the United States.
In its summary of results, the ECB did remind those pouring over its books that it still holds approximately €46 billion in net capital and what are referred to as revaluation accounts. With that number still being well above demand thresholds for the bank, the bank believes it still has more than enough to continue to carry out its primary mission of maintaining price stability and keeping regional banks solvent.
All that of course assumes there will be no run on this particular bank, such as could happen if yet another global crisis might cause serious harm to one or more economies in the EU or in the EU as a whole. Unfortunately for the ECB’s central planners, with the risks and costs of NATO's ongoing war on Russia, supply chain costs increasing in Europe once again because of Yemen's blockade of some shipping in the Red Sea, and the EU supporting Israel's continued genocide of Palestinians and attacks on Syria and Lebanon, there will be significant risks for the bank in 2024.